CofC: Consumer Discretionary - Retailing
From the 50th to the 83rd Percentile: Four Decades of Gasoline Prices
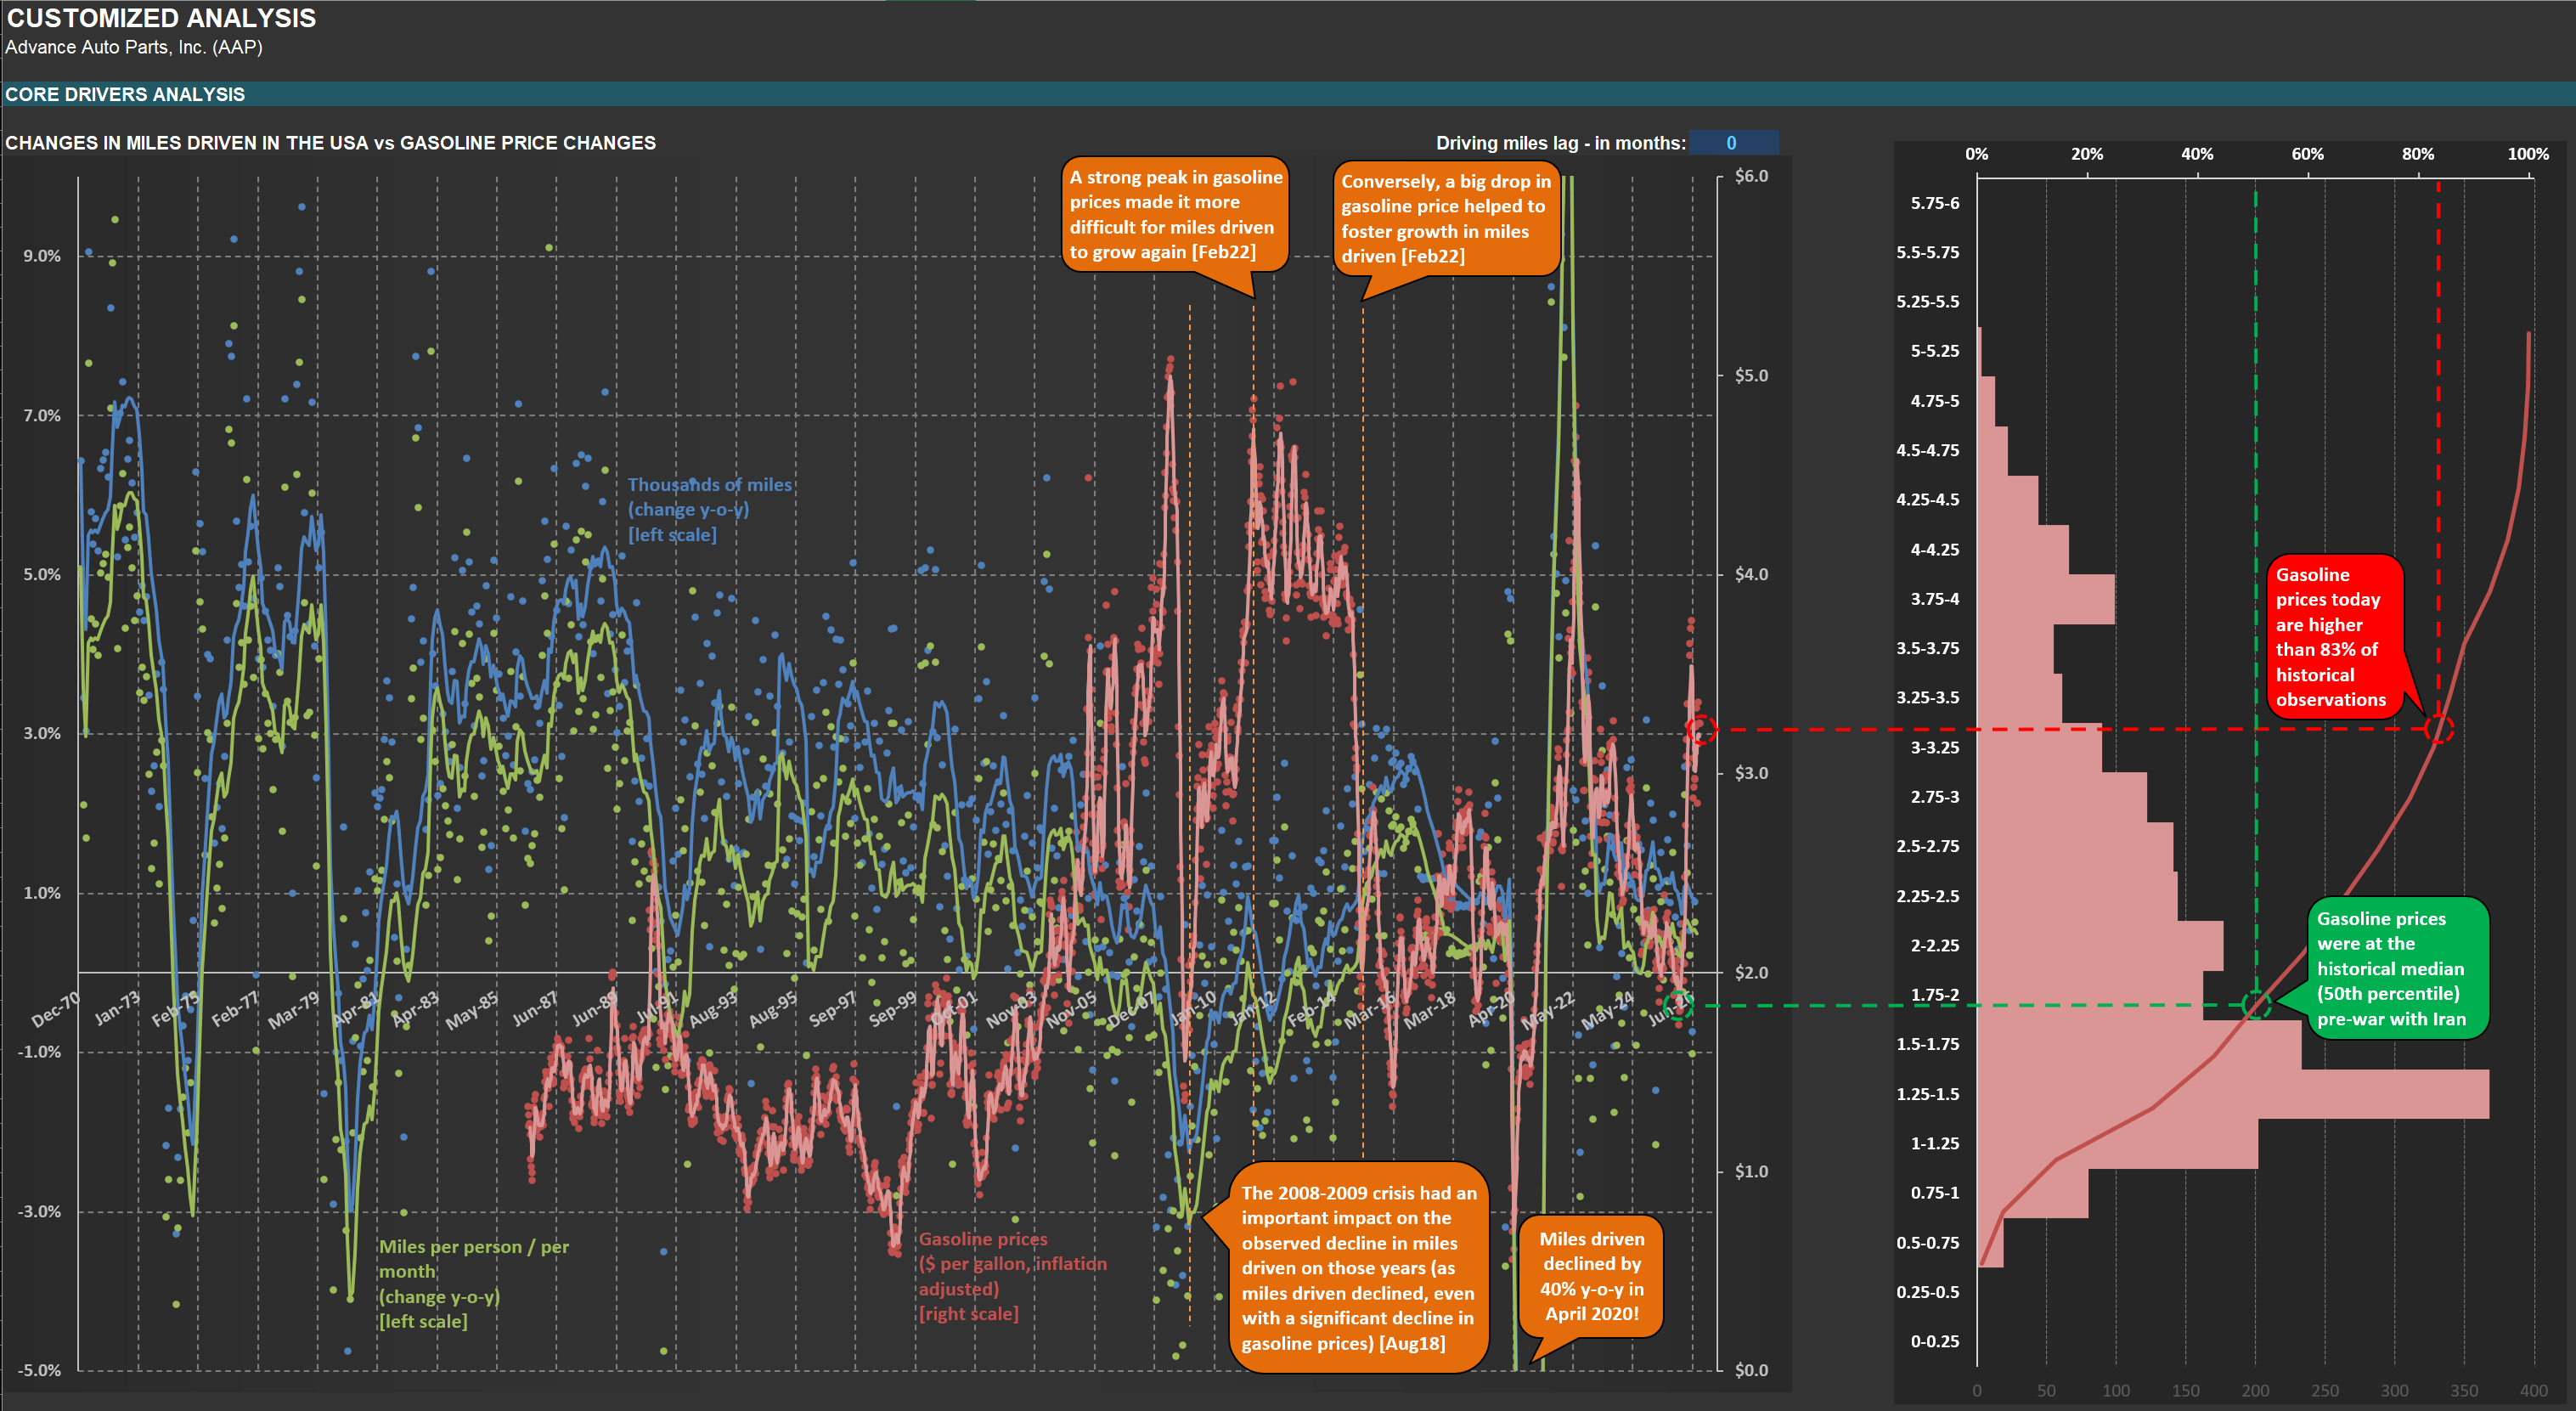
The chart below comes out of my work on $AAP (Advance Auto Parts), and it exists to answer one question: does the price of gasoline visibly change how much Americans drive?
That is not an idle question for an auto parts retailer. Miles driven are the raw input to the entire aftermarket — brake pads, filters, batteries, wiper blades, struts. I have shared the underlying miles-driven series here before (here), noting that miles per person peaked in 2005, two decades ago. What I want to do today is overlay the price at the pump on top of it and see whether the relationship people assume exists actually shows up in forty years of data.
Fair warning, as always: this is a working chart, not a presentation chart. It is busy on purpose. Take a minute with it.
What you are looking at
Start with the panel on the left, and with the three sets of dots, because they are the honest version of the data. Every dot is an actual reading. The blue dots are the year-over-year change in total miles driven in the United States. The green dots are the same figure on a per-person, per-month basis — which matters, because a country whose population is growing will naturally drive more miles in aggregate even if each individual drives less. The red dots are the price of gasoline, in dollars per gallon, adjusted for inflation, on the right-hand scale.
Now look at how much those dots scatter. Monthly readings of this kind are dominated by weather, holidays, the number of weekend days in a month, and revisions. Trying to read a trend off the raw prints is close to hopeless. That is why each series also carries a line: a 12-month moving average for the two miles-driven series (blue and green), and a 6-month moving average for gasoline prices (the pink line). The lines are what I actually read; the dots are there so I never forget how much noise sits underneath them.
One clarification on the price series, because it will otherwise trip up anyone who compares it to what they paid this morning. The gasoline price here is the spot quote at New York Harbor — a wholesale benchmark, not a pump price. What you pay at the station sits well above this line, since it carries federal and state excise taxes, distribution, and the retailer’s margin. But the correlation between the two is effectively 100%, so for the purpose of changes — which is what this chart is about — the benchmark does the job, and it has the advantage of a long, clean, daily history.
What the chart cannot show you: the 1970s
The first thing to acknowledge is a limitation. The miles-driven data begins in December 1970. The gasoline series does not — it starts in the mid-1980s, which is why the red dots simply do not exist on the left third of the chart.
That is a genuine loss, because the left third contains the two most dramatic collapses in the entire miles-driven history. You can see them plainly: a sharp fall in 1974, and an even more violent one running from 1979 into 1981, where the green line touches roughly minus 4.5% — the worst reading anywhere on the chart outside of April 2020. Had the price series reached back that far, it would have drawn two enormous spikes sitting directly on top of those declines: the Arab oil embargo of 1973–74, and the Iranian Revolution of 1979. Those are the two textbook oil shocks, and they are exactly where a gasoline-price explanation of driving behavior looks strongest.
But I want to be careful here, because there is a second explanation for those same two dips, and it has nothing to do with the pump. Housing construction collapsed in both episodes. Housing starts fell by more than half between 1972 and 1975, and then again between 1978 and 1982, when Paul Volcker took the Fed Funds rate toward 20%. Both periods were deep recessions. Fewer construction sites, fewer jobs, fewer deliveries, fewer commutes — and therefore fewer miles, regardless of what a gallon cost. I have made the broader point before that nearly every significant US downturn either began in housing or ran through it (here).
Two decades of cheap gasoline
From the late 1980s through the early 2000s, the pink line does something remarkable: almost nothing. For roughly fifteen years it oscillates in a narrow band, mostly between $1.25 and $1.75 a gallon in today’s money, with only brief interruptions — a spike around the first Gulf War, a dip to the series' lows in 1998 when Asia’s crisis knocked out demand.
This was the era of visible OPEC spare capacity. The demand destruction that followed the second oil shock, combined with new non-OPEC supply from the North Sea and Alaska, left the cartel sitting on millions of barrels a day of unused capacity for the better part of two decades. Prices behaved accordingly.
And what did miles driven do in that benign stretch? They grew — steadily, unremarkably, with the blue line running between roughly 1% and 3% for years on end and the green per-capita line comfortably positive. Cheap gasoline coincided with growth in driving. So far, so intuitive.
The mid-2000s, and a lesson about which variable wins
Then the pink line breaks out. Beginning around 2004 and accelerating through the late stages of the housing boom, real gasoline prices climb from under $2 toward $5 a gallon by mid-2008 — the highest sustained levels in the entire series. This is the same episode I have discussed from the crude side, when inflation-adjusted oil briefly exceeded $220 per barrel (here).
Miles driven decelerated through those years, and the per-capita line went negative well before the crisis. Advocates of the simple story will point at this and rest their case.
But then look at what happened next, because this is the single most instructive passage on the chart. Gasoline prices collapsed — from near $5 to below $2 in the space of six months, one of the fastest declines on record. And miles driven fell anyway. The blue line went to roughly minus 3%, the worst reading since 1980. Cheapest fuel in years, and Americans drove less.
That is the Great Financial Crisis overwhelming the price signal. When people lose jobs, they do not commute. When freight stops moving, trucks stay parked. When construction halts, the pickup does not leave the yard. The price of the fuel becomes a second-order consideration.
Now set that against the recession that preceded it, and the contrast is instructive in the opposite direction. The Internet bubble burst in March 2000 and the economy went into recession in 2001 — and you essentially cannot find it on the left panel. The blue line stays positive throughout. Miles driven simply kept growing. Yet freight did respond: trucking tonnage began declining in March 2000, right as the market broke, which is the episode I used to argue that a market crash can indeed trigger a recession (here).
Two recessions, two completely different signatures. The 2001 downturn destroyed financial wealth and corporate capital spending; it did not stop households from driving to work. The 2008 downturn destroyed household balance sheets, employment, and housing all at once — and it showed up in miles driven immediately, in defiance of collapsing fuel prices. If you want a single sentence out of the left panel, it is this: gasoline prices influence driving at the margin, but economic activity decides it.
April 2020
And then the exception that dwarfs everything. In April 2020, miles driven fell 40% year over year. There is no precedent for it anywhere in fifty-five years of data — the second-worst month in the series is not remotely close. It is the only observation on this chart that a moving average cannot civilize, which is why the green line shoots vertically off the top of the panel and back again.
Gasoline, meanwhile, reached one of the lowest points in the entire series. Demand simply evaporated; for a few extraordinary days, so did the price of the crude behind it. Once again: cheapest fuel in a generation, least driving in recorded history. The price was not the variable that mattered.
Which brings us to the present, and to the panel on the right.
The histogram: what “expensive” actually means
The right-hand panel takes every gasoline price observation in the series — roughly 2,100 of them, spanning about four decades — and sorts them into 25-cent buckets, in inflation-adjusted dollars. The horizontal bars are simple counts: how many times in forty years gasoline traded in each price range. The red line running up the panel is the cumulative distribution, read against the percentage scale along the top. At any price level, it tells you what share of the historical record sat at or below that price.
The shape is worth absorbing. The single most common bucket is $1.25–$1.50, with 368 observations. Nearly a third of the entire history — 31.8% — sits below $1.50. Half of it sits below the $1.75–$2.00 range, which is where the median lands. And only about 22% of all observations in four decades were ever above $3.00 a gallon in real terms.
Now the green dashed line. Immediately before the war, gasoline was sitting almost exactly on that median — the 50th percentile of its own forty-year history. Half of the entire record was cheaper; half was dearer.
I want to dwell on this, because “the median” sounds unremarkable and is not. The comparison set includes the whole OPEC-spare-capacity era of the late 1980s and 1990s — the years that Americans, correctly, remember as cheap-energy years. Pre-war prices were within striking distance of that period. Set against the mid-2000s, against 2011–2014, against the post-pandemic spike, the American driver going into this year was paying a genuinely benign price for fuel. In terms of energy costs, the consumer had it about as good as the historical record allows.
Where we are now
The red dashed line is today. Six months into the war with Iran, and with the Strait of Hormuz reduced to a trickle, the same benchmark has moved from the 50th percentile to above the 83rd — with peaks along the way that touched roughly the 93rd, up in the $3.75–$4.00 bucket in real terms. At the pump, the national average has gone from around $2.92 a gallon in late February to over $4.09, on its way to the highest August average ever recorded.
Read that as the histogram reads it: in the space of six months, American drivers have been moved from the middle of four decades of experience to the top sixth of it. Roughly one month in six, across forty years, has been this expensive or worse. That is the move, and it is not a rounding error.
Moves like this have consequences
Here is why I care about a chart built for an auto parts retailer.
The first consequence is the consumer, and readers of this blog know I have been making this argument for a long time and from many different angles. Gasoline is the most regressive line item in the American household budget — non-discretionary, purchased weekly, and consuming a far larger share of income at the bottom of the distribution than at the top. Every dollar added to a fill-up comes out of something else: a mattress, a boat, an RV, a set of brake pads, a pizza. I have shown the American consumer behaving recessionally for well over a year now, whether through RIM’s valuation distributions, where the cheap half of my Circle of Competence reached undervaluation levels last seen in 2011 (here), or through Harley-Davidson’s credit loss provisions, which have run elevated for years (here). This is a consumer who did not need an additional dollar-a-gallon tax.
The second consequence runs a longer route, and it is the one that worries me more. Energy prices are an input to almost everything, which makes them an input to inflation. US inflation moved from 2.4% in February to 3.3% in March, driven principally by the energy shock. Inflation, in turn, is the single most important driver of the 30-year mortgage rate — I laid out that chain, from federal deficits through inflation to the 10-year note and on to mortgages, in some detail (here). And mortgage rates are what determine whether the housing market functions at all.
It does not function well at the moment. Existing home sales have been stuck at levels last seen in 1995 (here) — the product of high prices meeting mortgage rates that are elevated relative to the past decade but entirely normal against any longer history, and of the lock-in effect that keeps homeowners with sub-3% mortgages from ever putting a sign in the yard (here). Anything that pushes inflation higher pushes mortgage rates higher, and pushes the eventual thaw further out.
So the chain is: a strait in the Persian Gulf, to the price at a station in New Jersey, to the household budget, to the inflation print, to the 10-year note, to the 30-year mortgage, to whether a young couple can buy their first house. It is not a subtle chain, and it is not a new one. It is worth remembering that this same conflict is already showing up in company results in ways that have nothing to do with driving — O-I Glass, for instance, booked $50–100 million of incremental energy inflation attributable to it (here).
The honest conclusion
The chart I set out to build was meant to test whether gasoline prices move miles driven. Forty years of data give a qualified answer: yes, at the margin, in the absence of anything larger — and no, decisively, whenever anything larger is happening. In 2008 and again in 2020, the price went one way and the driving went the other. Economic activity is the dominant variable, and it is not close.
Which is precisely why the current spike is worth watching. It is not the miles-driven line I am worried about. It is that a shock of this size, sustained for this long, is itself capable of becoming the larger thing — through the consumer’s wallet, through inflation, and through the interest rates that govern the most important asset most American families will ever own.
For now, we wait, and we hope for a durable resolution to the conflict — one that arrives before the damage compounds into something that shows up not just in the price of a gallon, but in the blue line itself.
$LOW [Lowe's] and the Visible Impact of Tax Policy
A company’s tax rate is often modeled as if it were broadly stable over time. Lowe’s shows that public policy can alter that baseline in a way that materially changes reported economics.
The chart below tracks Lowe’s GAAP and cash tax rates, adjusted for unusual items and pension-related distortions. For many years, both series sat at materially higher levels, generally in the high-30s to low-40s. Then the range broke lower.

That is not a minor fluctuation. It is a regime change. And the most obvious explanation is the Tax Cuts and Jobs Act, the late-2017 reform that cut the federal corporate tax rate to 21% for tax years beginning in 2018.
The distinction between GAAP taxes and cash taxes matters here. Cash taxes can run below GAAP taxes for meaningful stretches because companies work hard to defer payment, but the longer-run picture is more revealing: the 5-year moving averages in the chart show cash taxes tending to move back toward GAAP taxes over time. In other words, companies can often change the timing of taxes, but they have a harder time escaping the underlying economics indefinitely.
That is why the chart is so useful. It does not just show that Lowe’s cash taxes fell. It shows that both the accounting burden and the cash burden eventually reset lower, which makes the policy effect much harder to dismiss as temporary noise.
This also ties naturally to my recent post on the CHIPS Act, data centers, and semiconductors (here). The channel is different, but the lesson is the same: government decisions can leave visible fingerprints on corporate results. Here, that fingerprint runs through the tax line.
The real takeaway: good analysis is not just about reading reported numbers; it is about recognizing when those numbers are being shaped by a change in the rules of the game.
Cross-Checking Industry Trends: Lowe’s and Home Depot
The reason I follow multiple companies within the same industry is, among other things, to cross-check whether trends observed in one company are also evident in another. For example, take a look at the chart below, which illustrates $LOW (Lowe’s) sales per square foot. Focus on the green series—it represents sales adjusted for inflation and square footage growth. The adjustment for square footage growth is less significant now, as Lowe’s (and Home Depot) have largely saturated their markets. The second chart, which shows year-over-year sales per square foot, highlights the extraordinary growth in 2020—nearly 24%.
Now, compare this with what I recently wrote about $HD (Home Depot) (here). In the top chart, you’ll see a similar series for Home Depot’s sales adjusted for inflation and square footage growth (in red). Notice how closely the patterns align between the two companies?
These similarities suggest that both Lowe’s and Home Depot were impacted by the same macroeconomic trends during the pandemic. This indicates that neither company’s management was implementing uniquely effective strategies to drive sales during that period. Instead, the rapid growth was fueled by pandemic-related excesses, which are now tapering off.
Looking ahead, it’s a matter of waiting for the next unusual factor—whether positive or negative—that will influence sales. However, what truly matters when conducting meaningful analysis is finding arguments to support a long-term perspective. In the case of Lowe’s and Home Depot, understanding their market saturation is key. Spectacular growth is likely a thing of the past for both companies.

Benjamin Graham's Wisdom Applied: Why I Differ on $HD
I just finished updating my analysis on $HD (Home Depot), and the outlook for 2025 suggests it will mark the fourth consecutive year of declining sales per square foot, adjusted for inflation. The last comparable period of sustained decline was between 2006 and 2009. You can see this trend clearly in the chart below—focus on the red data series with dots.
This decline reflects the normalization following the post-pandemic boom. During that period, extremely low interest rates, substantial stimulus measures, and increased time spent at home drove a surge in sales for Home Depot and $LOW (Lowe’s). Even factoring in the additional $20 per square foot from Home Depot’s acquisition of HD Supply, my analysis assumes average sales will remain about $70 higher than pre-pandemic levels (see calculations below the first chart). I also assume (not shown in the charts) that the company will maintain healthy margins. I.e., if anything, I’m being aggressive in my forecasts.
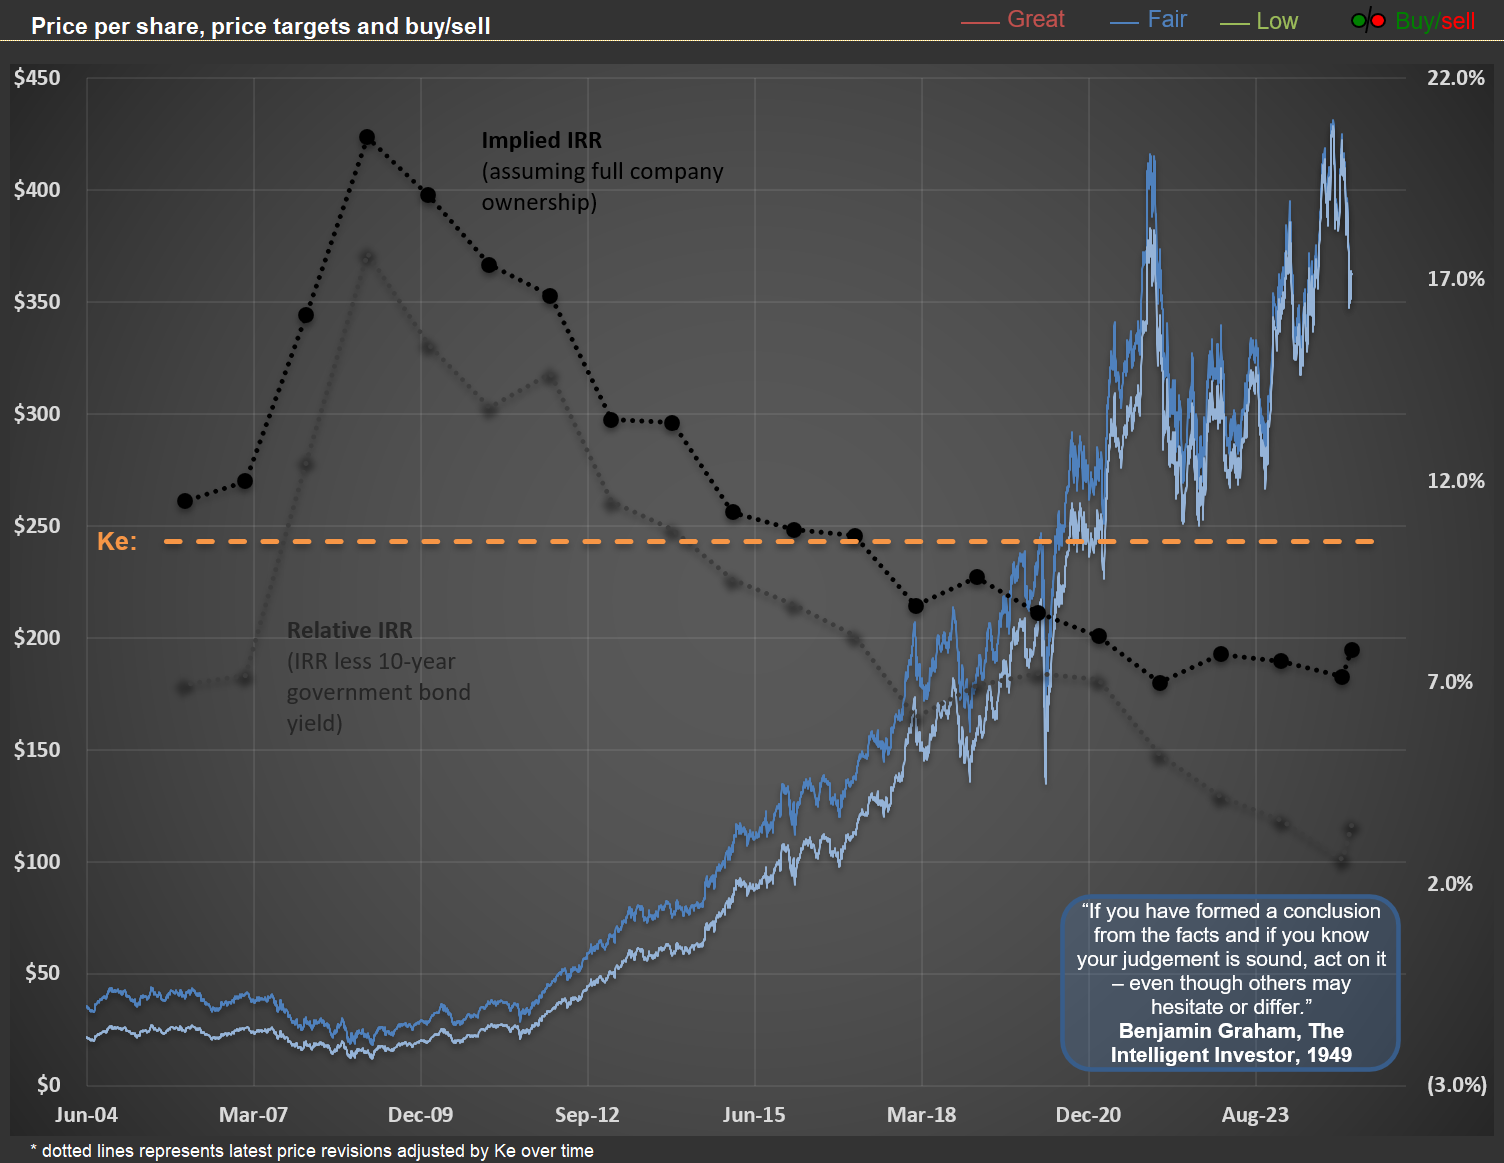
Despite this relatively optimistic assumption regarding future sales and margins, current share prices for HD suggest that long-term investors may achieve modest returns. Based on my base-case scenario, the future IRR (Internal Rate of Return) is projected to be approximately 7% per year. For context, you can read my earlier post on understanding implicit IRRs here.
The second chart below illustrates implicit IRRs for HD at 20 different year-end points. As expected, higher share prices correspond to lower IRRs—this is simply math. If your base-case scenario is well-calibrated, any given share price implies a specific IRR for long-term owners. Historically, the best time to buy HD (and LOW) shares was in 2009, when the implied IRR reached 20.5%. For perspective, this offered a real return (assuming an annual inflation rate of 2.5%) equivalent to multiplying your investment by five over a decade. I presented this analysis at a Value Investing Event in Trani, Italy, although few attendees were enthusiastic about these ideas at the time.
Today’s elevated prices prompt me to recall Benjamin Graham’s timeless advice from The Intelligent Investor, written in 1949: “If you have formed a conclusion from the facts and if you know your judgement is sound, act on it – even though others may hesitate or differ.” In contrast to many analysts nowadays, I believe $HD and $LOW are not attractive investments at current valuations. If sales continue to decline or fail to rebound meaningfully, perhaps the market will eventually acknowledge that these prices imply lower-than-deserved returns for holding these assets.
Are Investors Overpaying for Growth? O'Reilly's SSS Under the Microscope
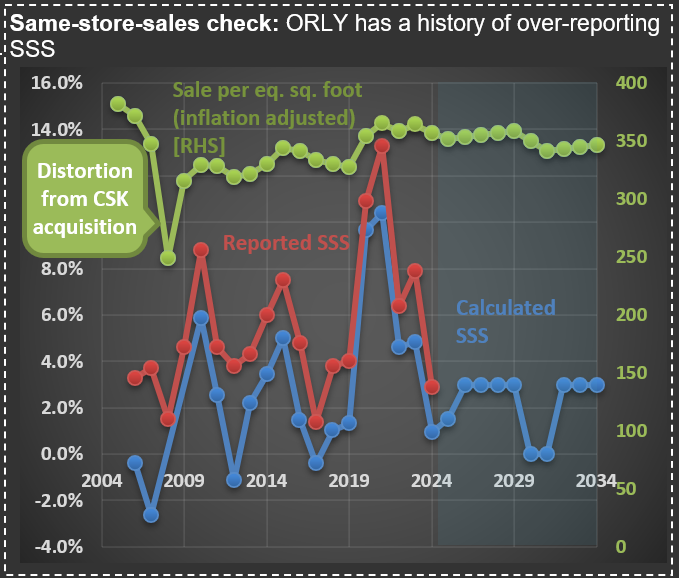
When analyzing retailers' sales, it is necessary to adjust “same-store sales” (SSS) by the age of the square footage. This adjustment is required because newer stores typically generate lower sales per square foot than established locations, as it takes time for customers to discover and frequent newly opened convenient locations.
Without these adjustments, there’s a significant risk of overestimating actual sales growth. In my analysis of $ORLY (O’Reilly Automotive), I’ve consistently calculated lower growth figures than what they’ve reported for several years now. As you can see in the picture below, ORLY’s reported figures (red line) consistently outpace the properly adjusted metrics (blue line).
Over the past two decades, ORLY has reported impressive average SSS growth of 5.6% annually. However, my calculations suggest they’ve overestimated this growth by approximately 2.9% per year. This means their true SSS growth rate is closer to 2.7%—essentially tracking with inflation.
This discrepancy may have contributed to ORLY’s current valuation, which stands at more than 30x earnings. At today’s price, an investor is accepting a potential return of only about 5.5% annually (from a business owner’s perspective, similar to how Warren Buffett would evaluate a complete acquisition). Is such a modest return sufficient for your investment goals?
Less cars but higher sales in real terms? Inflation confusion at play
After finishing my $AAP (Advance Auto Parts) work, I’m updating my analysis on $ORLY (O’Reilly Automotive). The difference in performance between these two stocks is staggering, but—given current price levels—you might be surprised which offers materially better prospects for higher IRRs (Internal Rate of Return) for the long-term holder.
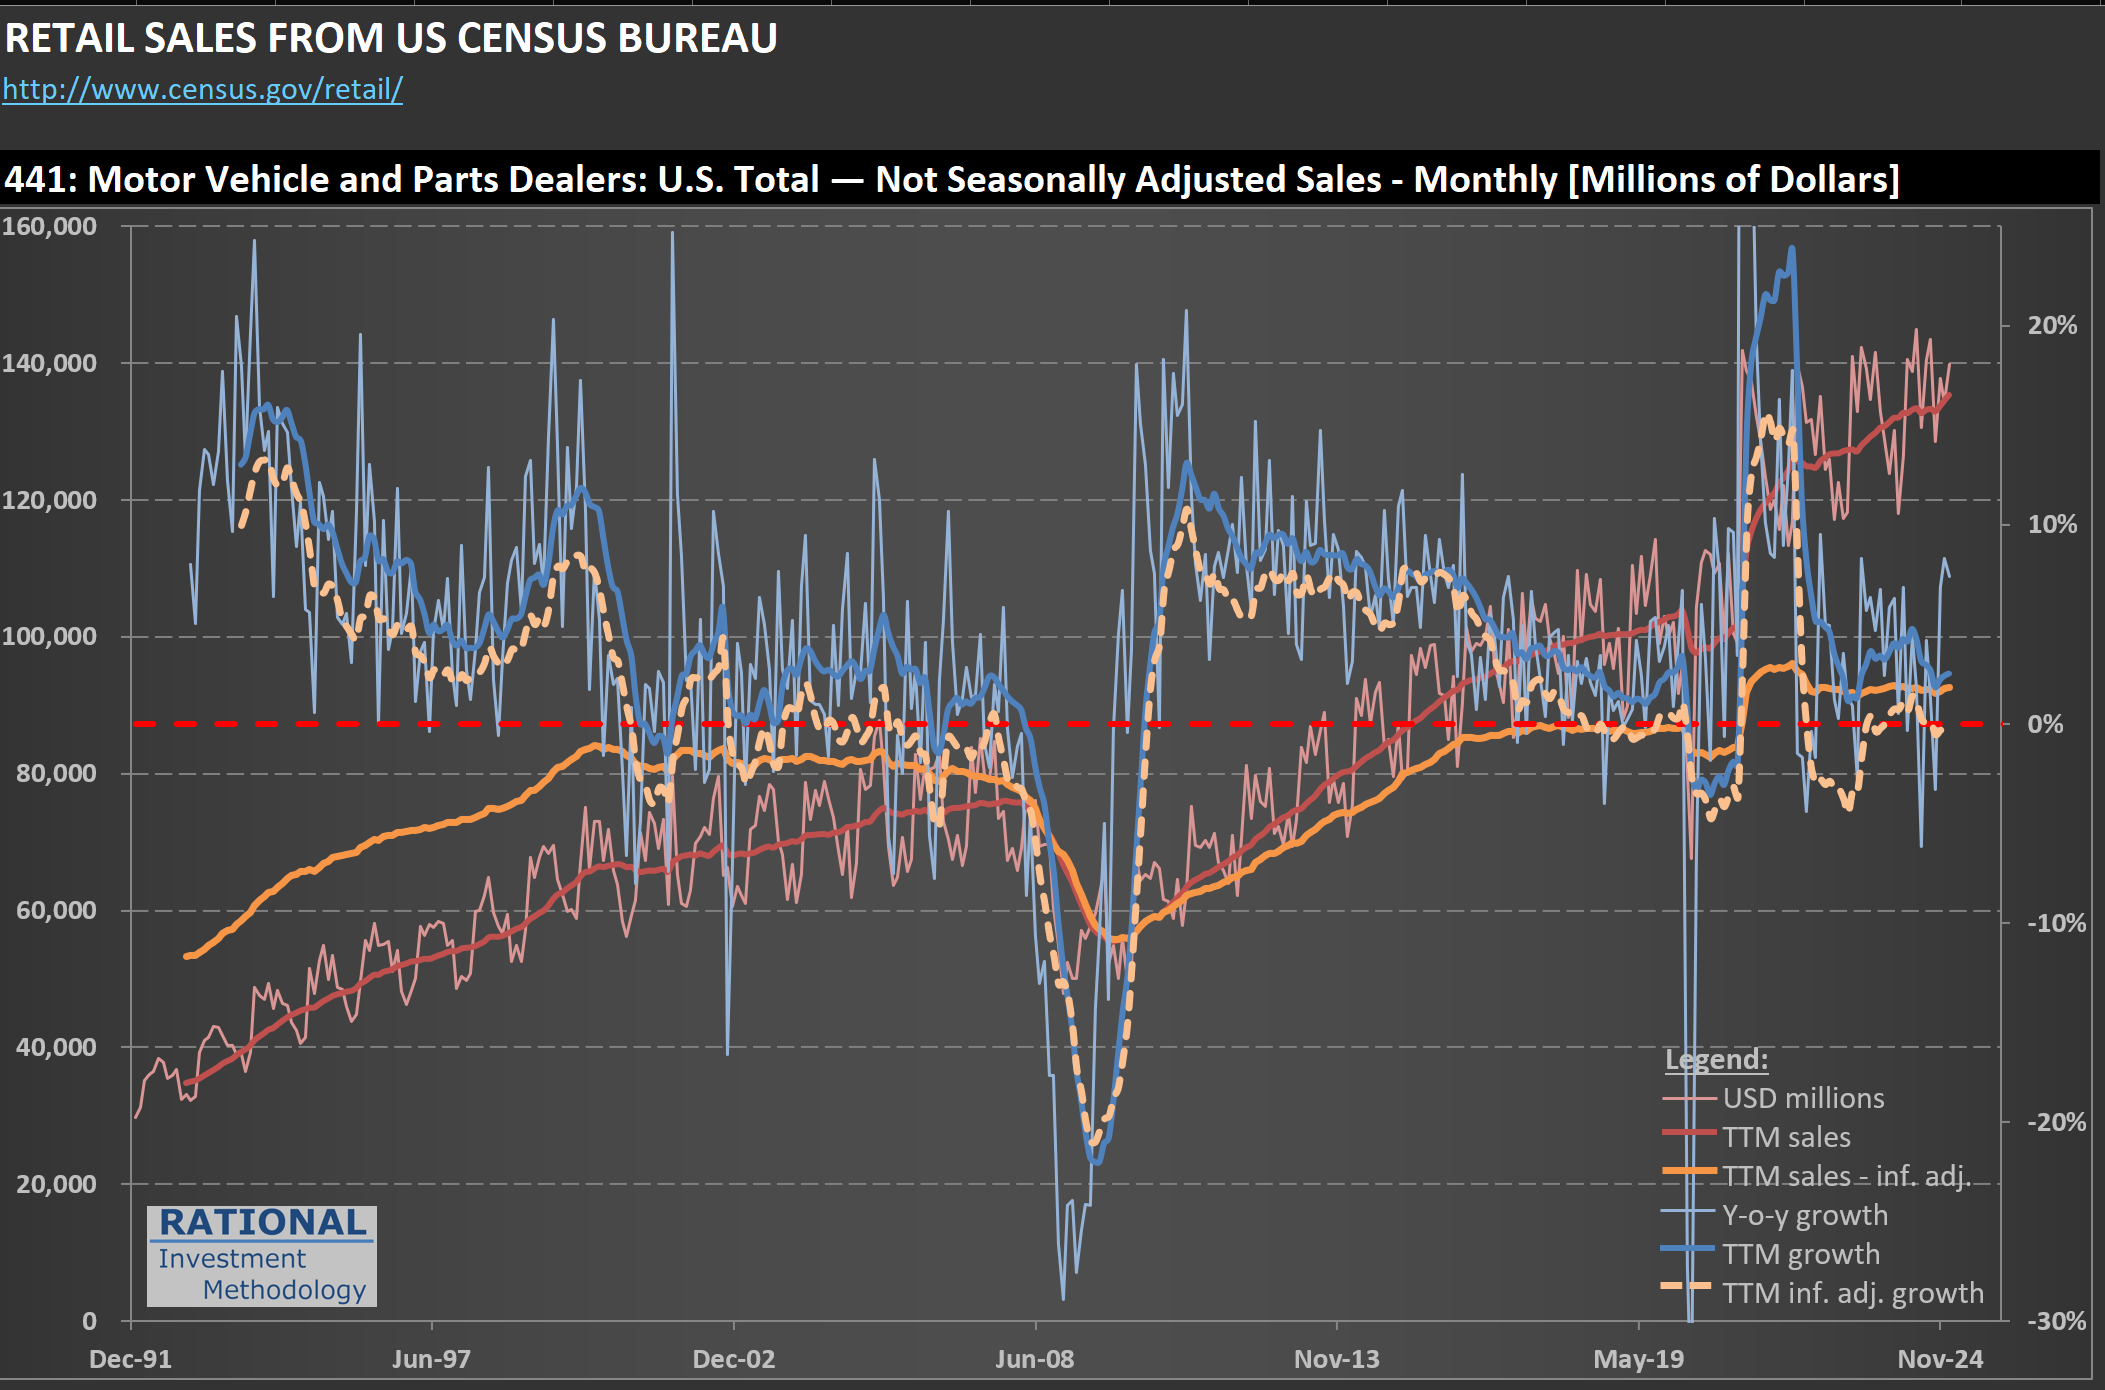
The chart I’m sharing below offers a high-level view of motor vehicle (and parts—a small part of these figures) sales. The line to focus on is the orange one: it shows sales adjusted for inflation. Now if you look at the last post (here) showing the number of vehicle sales, you will see a discrepancy. I.e., the number of vehicle sales is lower (by -7,5%) while the total dollars spent is higher (by +6.4%) compared to pre-pandemic levels.
A change in mix (more expensive cars, less cheap cars) could explain part of the delta. But another factor is at play: the overall inflation ratio (which I use to normalize sales) doesn’t capture the actual inflation in car prices. These more expensive (in real terms) cars lead to lower unit sales than before. It doesn’t help that the American consumer is also in a recession - I discussed it on a post yesterday (here).
Understanding long-term drivers for auto parts sales
I’m working on $AAP (Advance Auto Parts) today, one of the top three auto parts retailers - more on the business later. Now I’m sharing two charts I have in my analysis to ensure I’m aware of some secular trends affecting the industry.
The first shows total miles driven (in blue) and miles driven per person (in green). The lines are a trailing 12-month figure. Total miles driven still grows, but not by much. It is interesting to note, however, that miles driven per person peaked in 2005—two decades ago!
If people drive less, they should be buying fewer cars—at least per capita, right? We observe this in the data—see the second chart. The blue dots show cars sold per month. In red, an index of how many cars were bought per capita is shown. The peak of car purchases in the US happened in the summer of 1979! The last peak of absolute numbers of vehicles sold in 12 months happened 25 years ago, in the summer of 2000.
These figures help me calibrate the underlying potential auto parts sales. On top of the drivers I just shared, I still need to consider how long cars last nowadays. For example, if one observes that we have an “aging fleet” in the US and concludes that they are going to need more auto parts, that might not be the case if cars just last longer. Technology has made parts more durable. Hence you have to consider a cascade of effects when trying to understand what will impact sales in the long run.